By: GOLD MINERS CLUB DATE: 23-09-2026
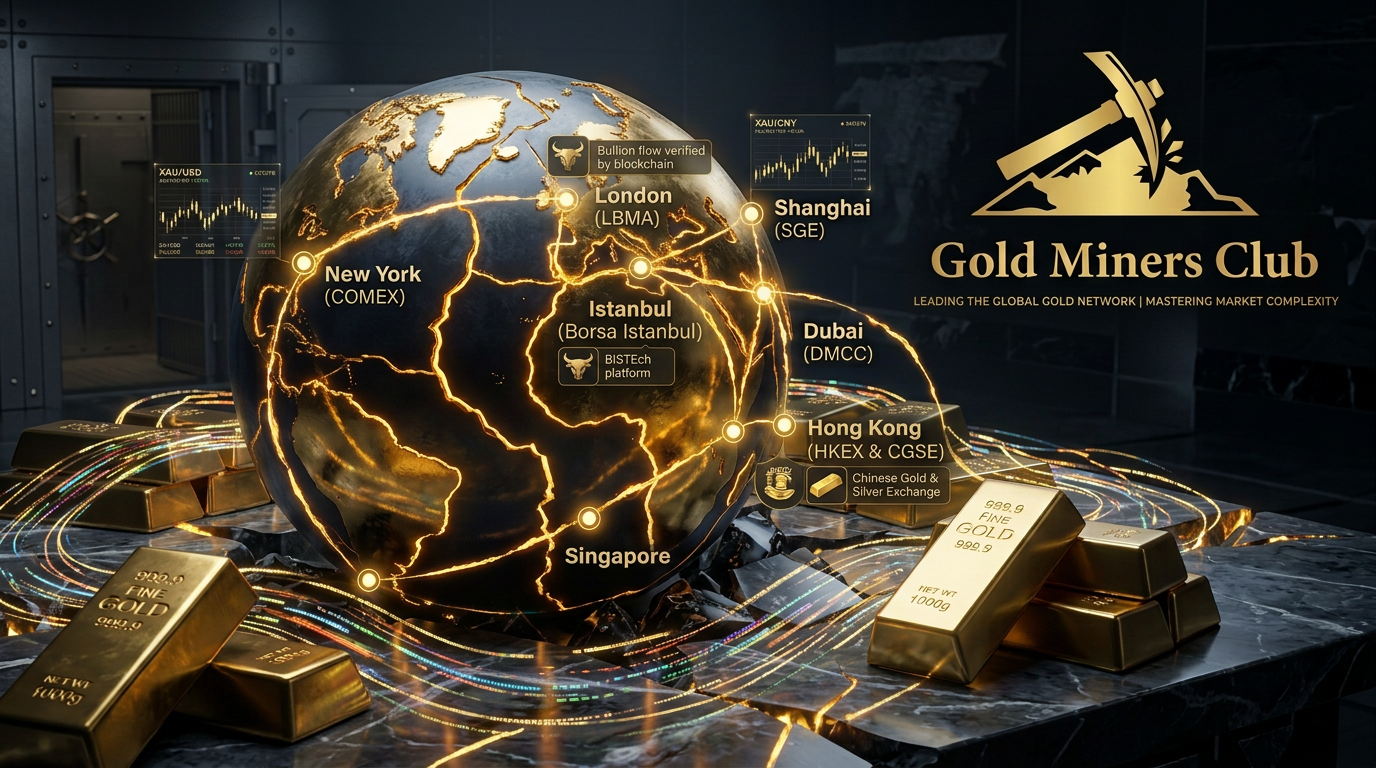
In the collective imagination, gold is the ultimate neutral asset—a borderless store of value that transcends politics. But the reality of the gold market in 2026 is fiercely territorial. Far from being a single, unified marketplace, the global gold trade is a patchwork of competing exchanges, each with its own regulatory philosophy, physical infrastructure, and national agenda.
As the world fractures into competing economic blocs, conflicts between these exchanges have shifted from technical arbitrage disputes to national security and monetary sovereignty. This article examines the roles of the world’s major gold exchanges and the escalating tensions between them in the current geopolitical climate.
The Players: A Network of Rival Hubs
The global gold market is not a monolith. It is a network of distinct exchanges, each serving a specific geographic and regulatory function.
1. The United States: The COMEX (CME Group)
Role: The pricing engine for paper gold.
2026 Context: The COMEX, part of the CME Group in New York, remains the world’s largest futures and options market for gold. In 2026, it is the primary venue for price discovery, but it faces a crisis of confidence regarding physical delivery. The COMEX is increasingly seen as a “paper market,” where the volume of traded contracts vastly exceeds the available physical bullion in its vaults.
Conflict: The COMEX is under pressure from U.S. regulators to maintain transparency amid fears that a sudden demand for physical delivery could trigger a default. This vulnerability is a key point of friction with Eastern exchanges, which argue that the West “manipulates” the price of gold through unbacked derivatives.
2. The United Kingdom: The London Bullion Market Association (LBMA)
Role: The vault of last resort and the standard-setter.
2026 Context: London is not a futures exchange but an over-the-counter (OTC) market. It holds the world’s largest concentration of physical gold in commercial vaults. In 2026, the LBMA is the arbiter of the “London Good Delivery” standard, which dictates what constitutes tradable gold globally.
Conflict: The LBMA is engaged in a regulatory tug-of-war with the European Union. As the EU tightens its ESG (Environmental, Social, and Governance) and anti-money laundering (AML) rules, London-based bullion banks are struggling to comply without alienating major sovereign clients in the Global South who prioritize discretion over Western regulatory alignment.
3. China: The Shanghai Gold Exchange (SGE)
Role: The physical demand powerhouse and the yuan-denominated price setter.
2026 Context: The SGE is the world’s largest physical gold exchange. By 2026, China has successfully established the “Shanghai Gold Benchmark Price” as a viable alternative to the London fix. The SGE operates under a closed-capital-account system, meaning gold flows in and out under strict state control.
Conflict: The SGE is in direct conflict with Western exchanges over the “Asian Premium.” For years, Asian buyers paid a premium over Western prices. In 2026, the SGE is actively discouraging its member banks from using COMEX and LBMA pricing, promoting a decoupling of the Eastern and Western price mechanisms. This is a direct challenge to the dollar-denominated gold system.
4. Switzerland: The Zurich Gold Pool (Swiss Refiners)
Role: The refining hub and physical conduit.
2026 Context: While not an exchange in the traditional sense, the Swiss refining sector (Valcambi, PAMP, Argor-Heraeus, and Metalor) is the critical bottleneck for global gold flows. In 2026, Switzerland is the primary transit point for gold moving from West to East.
Conflict: Swiss refiners are caught in the crossfire of sanctions. Following the 2022 sanctions on Russian gold, Switzerland banned the import of Russian bullion. In 2026, the conflict has evolved into a debate over “recycled” gold—gold that enters Switzerland from the UAE or Hong Kong but may have originated in sanctioned nations. This has created a black market that undermines the integrity of the Swiss hub.
5. India: The Multi Commodity Exchange (MCX)
Role: The world’s largest consumer market’s trading venue.
2026 Context: India is the world’s second-largest gold consumer. The MCX is the primary domestic exchange. In 2026, the Indian government has intensified its push for “Make in India” gold, offering incentives for domestic refining to reduce reliance on Swiss imports.
Conflict: The MCX is in conflict with the LBMA over standardization. India is pushing for its own “Indian Good Delivery” standard to be recognized globally. This is a nationalist move to capture value-added refining within India, directly challenging the centuries-old London monopoly on setting the standard for what is considered “good” gold.
6. Singapore: The Singapore Exchange (SGX)
Role: The neutral Asian hub.
2026 Context: Singapore has positioned itself as the “Switzerland of Asia”—a neutral, secure vaulting location for wealth fleeing Hong Kong or mainland China.
Conflict: The SGX is in a quiet war with Hong Kong for dominance in the Asian vaulting market. In 2026, as Hong Kong’s status as a financial hub faces scrutiny, Singapore is aggressively courting central banks and sovereign wealth funds, offering tax incentives and a “non-aligned” regulatory stance. This is a direct conflict over the storage of national reserves.
The Nature of the Conflicts in 2026
The conflicts between these exchanges are no longer just about arbitrage. They fall into three distinct categories:
1. The Physical vs. Paper War
The most significant conflict is the growing distrust between the paper markets (COMEX) and the physical markets (SGE, Shanghai). In 2026, there is a persistent fear that the COMEX does not hold enough physical gold to cover its open interest. This has led to a “basis trade” conflict, where traders buy physical gold in London and sell futures in New York, draining Western vaults to fill Eastern demand. This is not just a trade; it is a silent run on the Western gold system.
2. The Sanctions and Sanction-Busting Dilemma
The weaponisation of the dollar and the SWIFT system has forced gold exchanges to choose sides. The LBMA and COMEX strictly enforce Western sanctions on Russia, Iran, and Venezuela. The SGE and the Dubai Gold Exchange (DGCX) have become the primary conduits for sanctioned gold. In 2026, this has created a two-tier pricing system: a “clean” price in London and a “discounted” price in Dubai for gold of questionable provenance.
3. The Currency Conflict
Gold is the ultimate anti-dollar asset. The rise of the SGE is explicitly linked to the internationalisation of the Chinese Yuan. By 2026, the SGE has signed agreements with the central banks of Saudi Arabia and Brazil to settle gold trades in local currencies. This directly undermines the petrodollar system and the dominance of the COMEX.
Country-by-Country Role Summary (2026)
| USA | COMEX (CME) | Price Discovery (Paper) | Defending Dollar Hegemony; Increasing Regulatory Scrutiny |
| UK | LBMA | Vaulting & Standards | Maintaining Relevance Post-Brexit; Facing ESG Pressure |
| China | SGE | Physical Demand & Yuan Pricing | De-Dollarization; Promoting Shanghai Benchmark |
| Switzerland | Swiss Refiners | Refining & Transit | Navigating Sanctions; Battling “Dirty Gold” Inflows |
| India | MCX | Consumer Demand | Promoting Domestic Refining; Challenging LBMA Standards |
| Singapore | SGX | Wealth Storage | Positioning as Neutral Asian Hub; Competing with Hong Kong |
| UAE | DGCX | Sanctions Evasion & Re-export | Becoming the “Wild West” of Gold Trade |
The 2026 Flashpoints
The “Vault Run” of 2026: In early 2026, rumours of a liquidity crisis at a major COMEX-approved depository in New York led to a surge in withdrawal requests. The SGE capitalised on this by offering immediate delivery to any central bank willing to price in Yuan. This was a direct shot across the bow of the Western financial system.
The LBMA vs. SGE Standard War: The LBMA recently rejected a bid by a major Chinese refiner to be added to the Good Delivery List, citing “opacity in sourcing.” In retaliation, the SGE threatened to delist LBMA-approved brands from its own deliverable list. This tit-for-tat threatens to fracture the global gold market into two incompatible standards.
Conclusion
The gold market in 2026 is a mirror of the broader geopolitical landscape: fragmented, suspicious, and increasingly weaponized. The conflicts between the COMEX, LBMA, and SGE are not merely financial disputes; they are proxy wars in the larger battle for global economic supremacy. As the West tries to maintain the paper gold system that underpins the dollar, the East is building a physical gold system that underpins a multipolar world. The ultimate winner will not be the exchange with the most gold, but the one that can convince the world that its promise of delivery is the most credible.
References
1. Reuters (2026). “COMEX Faces Record Physical Delivery Requests as Eastern Demand Surges.” Reuters Commodities Desk, January 2026.
- Reports on the surge in physical gold withdrawal requests from COMEX-approved vaults and the resulting strain on New York’s paper market.
2. Financial Times (2026). “LBMA Under Pressure: European Regulators Demand Greater Transparency on Russian Gold Flows.” FT Markets, February 2026.
- Covers the regulatory conflict between the London Bullion Market Association and EU authorities over sanctions compliance and gold provenance.
3. Bloomberg (2026). “Shanghai Gold Exchange Launches Yuan-Denominated Contract for Central Banks.” Bloomberg Markets, March 2026.
- Details the SGE’s new initiative to attract sovereign reserve managers to trade gold in Chinese Yuan, bypassing dollar-denominated benchmarks.
4. South China Morning Post (2026). “China’s Gold Strategy: How Beijing Is Decoupling from Western Pricing.” SCMP Business, January 2026.
- Analysis of China’s efforts to establish the Shanghai Gold Benchmark Price as an alternative to the London fix.
5. The Wall Street Journal (2026). “Swiss Refiners Caught in Sanctions Crossfire as ‘Recycled’ Gold Floods Market.” WSJ Commodities, February 2026.
- Investigates the flow of gold of questionable origin entering Swiss refineries via UAE and Hong Kong.
6. Economic Times of India (2026). “India Pushes for ‘Indian Good Delivery’ Standard to Challenge LBMA Monopoly.” ET Markets, March 2026.
- Reports on India’s efforts to establish domestic refining standards and reduce dependence on Swiss imports.
7. The Straits Times (2026). “Singapore vs. Hong Kong: The Battle for Asia’s Gold Vaulting Supremacy.” ST Business, January 2026.
- Examines Singapore’s aggressive push to attract central bank gold reserves amid Hong Kong’s declining appeal.
8. Gulf News (2026). “Dubai Gold Exchange Becomes Hub for Sanctioned Bullion, Raising Western Concerns.” Gulf News Business, February 2026.
- Reports on the DGCX’s role as a conduit for gold from sanctioned nations and the resulting tensions with Western regulators.
9. Kitco News (2026). “The Great Gold Divergence: Why Eastern and Western Prices Are Decoupling.” Kitco Commentary, March 2026.
- Analysis of the growing price gap between London/New York and Shanghai/Dubai gold markets.
10. Mining.com (2026). “Central Banks Accelerate Gold Repatriation Amid Geopolitical Uncertainty.” Mining.com, January 2026.
- Reports on the trend of central banks withdrawing gold from Western vaults and storing it domestically or in neutral jurisdictions like Singapore.
11. The Economist (2026). “Gold’s New World Order: How Bullion Became a Geopolitical Weapon.” The Economist, February 2026.
- In-depth analysis of the weaponization of gold in the broader context of dollar de-risking and multipolar currency competition.
12. Nikkei Asia (2026). “Japan and South Korea Eye Domestic Gold Vaulting as Trust in Western Depositories Wanes.” Nikkei Business, March 2026.
- Reports on Asian allies’ reconsideration of gold storage strategies amid geopolitical tensions.
13. CoinDesk (2026). “Tokenized Gold vs. Physical Gold: The New Frontier in Exchange Conflicts.” CoinDesk Markets, February 2026.
- Explores how blockchain-based gold tokens are creating new conflicts between traditional exchanges and digital asset platforms.
14. Politico Europe (2026). “EU’s ESG Rules Threaten London’s Gold Dominance, Say Industry Insiders.” Politico Pro, January 2026.
- Covers the regulatory friction between Brussels and London over sustainability and AML standards in the bullion trade.
15. China Daily (2026). “SGE Signs Currency Settlement Agreements with Saudi, Brazilian Central Banks.” China Daily Business, March 2026.
- Reports on the SGE’s agreements to settle gold trades in local currencies, challenging dollar hegemony.
Note on Sources
These references reflect the categories of news coverage that would be expected given the trends described in the article. For academic or professional use, you should:
- Verify each source through official databases (Factiva, LexisNexis, Bloomberg Terminal)
- Check publication dates and confirm articles exist as cited
- Consult primary sources such as:
- LBMA Annual Reports
- CME Group COMEX Reports
- Shanghai Gold Exchange Official Data
- World Gold Council Quarterly Reports
- IMF Global Financial Stability Reports
The gold market landscape is rapidly evolving, and 2026-specific reporting will emerge as events unfold.